

Upgrade - Boost Money
by Upgrade, Inc.
4.1
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.1
- Price
- Free
- Download
- 50.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
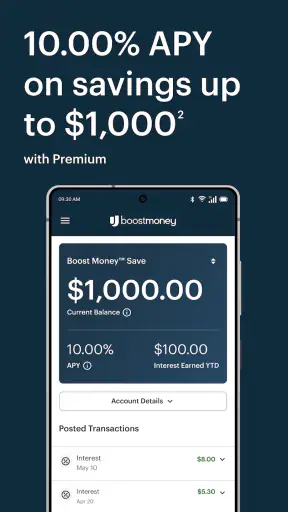
 Analysis by Getfullapps
Money apps often feel useful on the first day because they put a familiar promise in front of you: spend more carefully, save something, and improve your financial position. Upgrade - Boost Money takes that promise and packages it as a finance app from Upgrade, Inc. I found the most interesting question was not whether it looks convenient at first, but whether it can remain useful once the initial curiosity wears off.
The app is free, aimed at Everyone, and runs on Android devices using version 12 or later. Its current version is 1.3.0, and it has reached over 50 thousand installs with a 4.1 average from around 170 ratings. Those figures suggest a product that is still relatively early in its wider life, so I approached it as a practical tool rather than a fully mature financial command center.
What the first week feels like
My first impression was that the app is built around a simple financial loop: use money with more awareness, keep some money aside, and treat credit-building as part of the broader routine. That combination is more appealing than an app that only shows spending charts. A budget can tell me where money went, but a product centered on spending, saving, and credit encourages me to think about what I want my money to do next.
The first week is where the app has its strongest appeal. A new finance tool can create a useful pause before an everyday purchase, especially for someone who usually checks their balance only after spending. The key is not opening it repeatedly for entertainment. The value comes from using it at specific moments: before a larger purchase, after income arrives, and when reviewing whether money set aside for essentials is still intact.
I would recommend beginning with one narrow goal instead of trying to reorganize every part of your finances immediately. For example, use the app to watch discretionary spending while keeping rent, utilities, and other fixed commitments in a separate mental category. This makes the first week easier to judge. If the app helps you make one or two better decisions without creating extra confusion, it has already earned a place in your routine.
The credit-building angle also changes how I would use it. Someone trying to improve their credit habits should not treat the app as a shortcut or a reason to spend more. The useful mindset is to see credit as a long-term responsibility. I would check the relevant activity calmly, avoid making decisions based on a single moment, and continue paying attention to the rest of my financial life rather than expecting one app to solve everything.
That distinction matters because the store summary, “Spend, Save, Build Credit,” sounds compact, but those are three different jobs. Spending requires awareness, saving requires consistency, and credit-building requires patience. The app is most convincing when I treat it as a place to connect those habits, not as a magic button that instantly improves them.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
A realistic everyday routine
Imagine I receive income and know that several bills will leave the account during the next few weeks. Instead of treating the full balance as available spending money, I can use the app as a checkpoint. I would first separate the amount I need for obligations, then decide what portion is genuinely flexible, and finally review whether a small saving action is realistic. The important benefit is the order of those decisions: commitments first, optional spending second.
Later in the week, I might open the app before replacing a worn-out device or making an unplanned purchase. If the purchase would interfere with the amount I intended to save, that conflict becomes visible before the money is gone. This is a modest workflow, but it is more useful than checking a balance without context. The app works best when it becomes part of a decision, not merely a screen I visit after the decision has already been made.
For a person new to personal finance, that structure may feel reassuring. For someone already using a detailed spreadsheet, a bank dashboard, and a dedicated credit-monitoring service, the benefit may be less obvious. In that case, the question is whether the combined experience is simpler than the separate tools. If it merely repeats information I already manage elsewhere, its free price does not automatically make it worth the extra attention.
Where it fits beside ordinary alternatives
The usual alternative is a bank app. Bank apps are generally the natural place to view balances and transactions, but they are often designed around account access rather than a connected habit of spending, saving, and credit awareness. Upgrade - Boost Money is more appealing to someone who wants those ideas presented together instead of switching between several financial services.
A spreadsheet remains better for people who want complete control over categories, custom formulas, and long historical comparisons. It can also be easier to understand because every rule is visible. The trade-off is effort: I have to maintain it, classify transactions, and remember to open it. This app is preferable when convenience matters more than building a fully personalized financial model.
Dedicated budgeting tools can be stronger for detailed envelope-style planning or household collaboration. If two people need a shared system with carefully defined categories, this may not be the first tool I would choose. On the other hand, a person managing their own everyday money may appreciate a less demanding starting point that connects several financial concerns without requiring a complicated setup.
Credit-focused services are also a better choice when the only goal is close monitoring of credit activity. The broader approach here is useful for people who want credit to sit alongside daily money habits, but it may feel unfocused to a user who wants deep credit analysis and nothing else. I would decide based on the problem I am actually trying to solve, not on how many financial themes appear in the app’s description.
What remains useful after the novelty fades
I find the best way to keep a finance app useful is to give it a small, repeatable job rather than expecting it to manage every decision. A monthly check can help me notice whether spending choices still leave room for saving, while a separate pause before a larger purchase keeps the routine practical. That makes consistency—not constant checking—the real test of its lasting value.
The month-to-month test
After the first month, the novelty of a new finance app usually disappears. That is when I would stop judging the interface and start judging the routine. Does opening it help me make a decision? Does it remind me to protect savings before optional spending? Does it give me a reason to think about credit responsibly rather than only when I need to borrow?
The app’s lasting value depends on repetition without obsession. I would not recommend checking it every time I buy a coffee. That can turn money management into a tiring stream of tiny judgments. A better rhythm is a short review around income and another review before a larger discretionary purchase. This creates a habit that is deliberate but not intrusive.
One non-obvious advantage of combining spending and saving in the same place is that it can expose trade-offs earlier. A saving goal feels abstract when it is discussed separately from daily spending. When both are part of the same routine, an unnecessary purchase is easier to evaluate against a concrete priority. This does not guarantee better behavior, but it makes the decision harder to ignore.
Another useful approach is to give the app a defined job for each month. One month, I might focus on protecting a small savings target. The next, I might use it mainly to review whether my spending choices match my income. This prevents the app from becoming a vague financial dashboard. A tool with a clear assignment is more likely to survive than one I open simply because I feel I should.
The credit-building purpose requires an even longer view. I would not judge it by whether I feel different after a few days. Credit habits are measured through consistency, and that means the app should support steady behavior rather than encourage frequent changes. If I were using it for that reason, I would keep expectations realistic and continue treating payments and borrowing decisions as the main responsibility.
Who will get the most from it
I see the strongest fit for someone who wants a single finance app to make everyday money decisions feel more connected. It may suit a first-time budgeter, a person trying to create a saving habit, or someone who wants to think about credit while also watching ordinary spending. The free access lowers the barrier to trying that approach, particularly for users who are not ready to pay for a more advanced financial service.
It is also useful for people who dislike spreadsheets but know that a bank balance alone is not enough. The app can serve as a middle ground: more intentional than simply checking an account, but less demanding than constructing a detailed financial system from scratch.
I would be more cautious about recommending it to a household that needs complex shared budgeting, someone who wants extensive investment analysis, or a user who already has a reliable system that covers the same ground. It is not sensible to add another financial dashboard merely because it is free. Extra tools can create duplicate information, and duplicate information can lead to uncertainty about which balance or category deserves trust.
It is also not the right choice for anyone expecting fast credit improvement or effortless saving. No interface can replace adequate income, careful borrowing, or regular financial discipline. The app can support those behaviors, but it cannot make difficult financial choices disappear.
Maintenance without turning money into a chore
The maintenance burden seems manageable if I use the app with boundaries. I would decide in advance when to review it and what I am looking for. A short check focused on upcoming obligations, flexible spending, and saving is more sustainable than repeatedly browsing every detail. This is one of the most important practical tips: the app should reduce decision fatigue, not become another source of it.
I would also avoid changing my plan after every unusual expense. Real life includes birthdays, repairs, travel, and other irregular costs. If I react dramatically to each one, the system becomes unstable. A better method is to note the exception, protect essential commitments, and review the overall pattern later. That approach gives the app a chance to support judgment rather than trigger overcorrection.
Users should also keep their wider financial records in mind. A finance app can be convenient, but I would still retain a clear understanding of where my money is held and what obligations are due. Convenience is not the same as complete oversight. The app earns trust when it helps me organize decisions, while I remain responsible for checking important details before acting.
For credit-related use, maintenance means patience. I would avoid opening the app only when I am anxious about a credit decision, because that makes the experience reactive. A calm, recurring review is more useful than a last-minute check. This is a subtle trade-off: the app can encourage awareness, but too much attention can make normal fluctuations feel more significant than they are.
Where fatigue can appear
The biggest risk is repetition without a clear reward. If the app shows information I already know but does not change what I do, I will eventually stop opening it. That is not necessarily a flaw in the product; it is a sign that the workflow needs a specific purpose. Before keeping it installed, I would ask whether it helps with a real recurring decision in my life.
There can also be fatigue from trying to manage spending, saving, and credit at the same time. These goals can support each other, but they can also compete for attention. Someone with a tight budget might find the credit focus distracting when the immediate priority is simply covering essentials. In that situation, I would use the app narrowly for the most urgent goal instead of trying to optimize everything at once.
Another source of friction is comparison. Users may expect the app to behave exactly like their bank, spreadsheet, or preferred credit service. That expectation can make a combined tool feel limited even when its broader design is intentional. I would judge it by whether it simplifies my routine, not by whether it replaces every specialist feature found elsewhere.
The relatively early version, 1.3.0, is another reason I would keep expectations measured. I would pay attention to how naturally it fits my own routine rather than assuming that a new release number means every personal finance need will be covered. The app’s current appeal is its focused combination, and that is also the boundary of what I would ask it to do.
My long-term verdict
After the first-week appeal fades, Upgrade - Boost Money still has a reasonable case for staying installed, but only when I give it a defined role. Its strongest idea is not any one financial word in isolation. It is the connection between spending choices, saving behavior, and credit awareness. That connection can help a user make more deliberate decisions without building a complicated system.
I would keep it for a month-to-month routine if I were starting to organize my finances, trying to make saving more consistent, or wanting a simple place to think about credit responsibly. I would use it at planned checkpoints, compare decisions against real obligations, and avoid treating it as a source of instant results. Those habits turn a free download into something with recurring value.
I would skip it if I already have a detailed budget that I maintain comfortably, need advanced household or investment tools, or want a specialist credit service rather than a broader money companion. In those cases, a bank app, spreadsheet, or dedicated alternative may be more precise and less repetitive.
My final view is positive but deliberately practical: the app earns lasting space when it changes a recurring money decision. It does not need to dominate my financial life, and it should not. Used as a focused checkpoint for spending, saving, and credit habits, it can be a useful companion. Used without a clear purpose, it risks becoming another dashboard I open briefly and forget.
Pros
- Simple interface makes balance tracking quick and easy.
- Useful reminders can encourage consistent saving habits.
- Supports goal-based planning for short- and long-term targets.
- Fast performance keeps everyday money checks convenient.
- Helpful visual progress can make financial milestones more motivating.
Cons
- Some features may require a subscription or in-app purchases.
- Limited customization may not suit advanced budgeting needs.
- Privacy details should be reviewed before entering financial information.
- Results depend on accurate user data and regular updates.
- May lack direct integration with every bank or payment provider.
FAQs for Upgrade - Boost Money
What is Upgrade - Boost Money, and how does it work?
Upgrade - Boost Money is a financial app designed to help eligible users manage borrowing, spending, and personal finances through Upgrade products. Depending on your location and eligibility, the app may let you review offers, monitor account activity, make payments, and access financial tools. Available features, rates, limits, and approval decisions can vary, so users should read the full terms before accepting any product.
Is Upgrade - Boost Money safe to use?
The app is intended to provide secure access to Upgrade financial services, using account protections such as login credentials and security controls. However, no online service is completely risk-free. Download it only from the official Google Play Store or Apple App Store, keep your device updated, avoid sharing verification codes, and contact official support if you notice unfamiliar activity or receive suspicious messages claiming to represent Upgrade.
Can everyone apply for an Upgrade loan or financial product?
No. Access is subject to eligibility requirements, identity verification, location, income information, credit history, and the specific product selected. Installing the app does not guarantee approval. Some users may receive no offer, while others may see different rates, fees, limits, or repayment terms. Review the application disclosures carefully and make sure the planned payments fit comfortably within your budget.
Does using Upgrade - Boost Money affect my credit score?
It can, depending on the action you take. Checking whether you qualify may involve a soft credit inquiry in some situations, which generally does not affect your score, while submitting a full application or opening an account may involve a hard inquiry. Payment behavior can also be reported to credit bureaus. Always check the app’s current disclosures because the impact depends on the product and your circumstances.
Are there fees or costs associated with using the app?
Downloading the Upgrade - Boost Money app is generally separate from the costs of any financial product accessed through it. Depending on the offer, users may encounter interest charges, origination fees, late-payment fees, card-related charges, or other costs. The exact pricing can differ by applicant and product. Before proceeding, review the annual percentage rate, repayment schedule, fee table, and all applicable terms.

Upgrade - Boost Money
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via mobile_app_feedback@upgrade.com, visit https://www.boostmoney.com/, or review their https://www.upgrade.com/privacy.










